Standard market roundups treat inflation prints, corporate earnings, consumer surveys, and Federal Reserve commentary as a checklist of separate events occurring on the same calendar. That framing misses the structural transmission belt connecting them. A price shock hits household budgets and logistics costs, reshapes corporate margin and capital-expenditure decisions, fractures consumer confidence along wealth and portfolio lines, and forces central bankers to weigh persistent price pressure against labor and financing fragilities.
To analyze this collision rigorously, this breakdown maps the underlying logic of conventional coverage, exposes where that logic stops short, and rebuilds the problem around four analytical pillars: The Inflation Pass-Through Matrix, The Bifurcated Household Balance Sheet, The Earnings-to-Capex Feedback Loop, and The Central Bank Reaction Function. Discover more on a connected topic: this related article.
Audit of Conventional Market Logic and Its Blind Spots
Typical weekly market previews follow a predictable sequence. They note that inflation remains sticky, consumer confidence looks fragile, corporate earnings are arriving in volume, and Federal Reserve officials face a balancing act between prices and employment. As a quick orientation to the week's calendar, that summary is serviceable. As an analytical model, it has three structural weaknesses.
First, it treats headlines as additive rather than interactive. Higher energy and diesel costs do not merely sit in an inflation index; they alter freight and warehousing expenses, squeeze operating margins for goods distributors, and compete directly for discretionary wallet share. Similarly, equity market swings tied to artificial intelligence spending do not exist in isolation from household sentiment or credit spreads. Additional journalism by Forbes highlights related perspectives on this issue.
Second, it conflates aggregate averages with economic behavior. Headline consumer sentiment or headline retail sales can mask sharp divergence underneath. A household whose real disposable income is pressured by essentials behaves differently from a household whose financial outlook moves with equity portfolios or asset valuations. Treating "the consumer" as a single monolith blurs both spending durability and survey signals.
Third, it frames central bank policy as a simple tug-of-war between inflation and jobs. In practice, monetary policymakers evaluate inflation persistence, inflation expectations, labor market slack, interest-sensitive sectors such as housing, and financial stability risks—including credit conditions and debt-financed capital spending—simultaneously. Reducing that multi-variable decision to a two-sided slogan obscures which transmission channels actually drive policy moves.
Pillar 1: The Inflation Pass-Through Matrix
Inflation is rarely a single uniform wave; it moves through distinct channels with different speeds and persistence. To evaluate how a busy macro week affects prices, separate cost-push logistics, sectoral supply bottlenecks, and expectations anchoring.
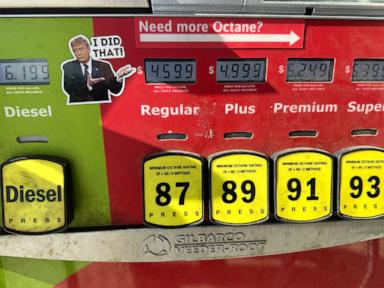
- Energy and freight pass-through: Geopolitical supply disruptions and elevated energy prices raise fuel and diesel costs. Because diesel underpins freight transport and warehousing, shipping costs act as a tax across physical supply chains. Whether businesses absorb that cost or pass it to buyers depends on pricing power and demand elasticity.
- Sectoral demand strain: Rapid capital investment in compute and data-center infrastructure can tighten supply chains for hardware, electrical equipment, and related goods, creating localized price pressure even when broader goods disinflation is attempted elsewhere.
- Services and shelter stickiness: Non-housing market services and housing costs often respond more slowly to initial supply shocks than raw commodities, while remaining sensitive to wage growth and financing rates.
- Short- versus long-run expectations: Near-term inflation expectations tend to react quickly to visible prices like fuel and groceries, whereas longer-horizon expectations indicate whether households and markets view elevated inflation as temporary or entrenched.
Cause-and-Effect Chain: From Fuel and Input Costs to Margin Compression
When fuel and logistics expenses rise, a firm faces an operational choice: raise unit prices, accept lower gross margins, or cut discretionary overhead. Raising prices protects near-term margins only if customers accept the higher price without reducing volume. When consumers push back against higher prices, revenue growth slows while per-unit fixed costs rise. That mechanism explains why a period of sticky inflation can coincide with uneven corporate earnings even before broad recessionary layoffs appear.
Pillar 2: The Bifurcated Household Balance Sheet
Consumer mood and spending rarely move in lockstep because households experience inflation and asset volatility through different balance-sheet structures. A rigorous reading of consumer data requires separating cash-flow sensitivity from wealth-effect sensitivity.
Cash-Flow and Essential Cost Pressure
For households where wages and everyday bills dominate monthly cash flow, essentials—energy, food, transportation, shelter, and borrowing costs—claim a large share of income. When prices for necessities stay elevated while real wage gains are thin or uneven, households have two primary adjustment levers:
- Trade-down and category reallocation: Buyers shift from higher-margin brands to lower-cost alternatives or value retailers, and trim discretionary categories to preserve spending on priority occasions or essentials.
- Buffer drawdown or credit reliance: When real disposable income is squeezed, some households draw down savings buffers or carry revolving balances, making debt-service costs a heavier drag if interest rates remain high.
Wealth-Effect and Portfolio Volatility
For households with substantial equity or financial asset holdings, sentiment is heavily shaped by asset prices and market swings. When equity markets experience sharp drawdowns or heightened volatility—particularly around concentrated themes such as artificial intelligence—wealthy households can report softer financial confidence even if essential fuel or grocery costs are not their primary budget constraint. Conversely, lower fuel prices can relieve cash-flow pressure for lower- and middle-income households even while equity volatility weighs on top-tier portfolios.
Analytical Distinction: A rise in nominal spending does not automatically prove broad economic strength. Higher prices on non-discretionary items can lift nominal outlays while reducing real unit volume or compressing household savings.
Pillar 3: The Earnings-to-Capex Feedback Loop
Corporate earnings reports during a macro-heavy week serve two functions: they report backward-looking operational performance, and they reveal forward-looking capital allocation under tight financial conditions.
Reading Earnings Beyond Headline Beats and Misses
Headline earnings per share can be distorted by share buybacks, tax items, one-time charges, or cost-cutting that cannot be repeated indefinitely. Analysts evaluating earnings in an inflationary, rate-sensitive environment should examine four operational signals:
- Volume versus price mix: Is top-line growth coming from higher unit volumes or purely from price increases? Price-led growth with flat or falling volumes signals fragile demand elasticity.
- Gross margin resilience: Are input, freight, and labor costs outpacing price realization, or are productivity gains offsetting cost inflation?
- Capital expenditure guidance and funding mix: Are companies scaling back capital projects due to higher borrowing costs, or pushing aggressive capital plans financed through operating cash flow, debt issuance, or off-balance-sheet commitments?
- Credit and financing sensitivity: When capital spending relies heavily on external financing or complex structured arrangements, any widening in credit spreads or skepticism over return on invested capital can quickly cool investor appetite.
Why Market Dispersion Matters More Than Index Averages
Equity indices can mask sharp internal divergence. Sectors tied to domestic discretionary spending or rate-sensitive credit behave differently from capital-intensive technology infrastructure or defensive value segments. When investors question the payoff timeline or financing strain of heavy capital expenditure programs, valuation multiples compress first in high-expectation areas while cash-generative businesses with disciplined balance sheets draw relative support.
Pillar 4: The Central Bank Reaction Function
When inflation stays above target while growth, labor data, and financial markets send mixed signals, central bank communication becomes a primary market catalyst. Policymakers do not react to a single data point in isolation; they weigh trade-offs across competing risks.
The Core Trade-Offs Facing Policymakers
- Price stability versus growth and employment: Keeping policy restrictive or tightening further helps contain persistent inflation and anchor expectations, but raises borrowing costs for households and businesses and can cool hiring or interest-sensitive sectors like housing.
- Supply-driven noise versus demand persistence: Central bankers try to distinguish between temporary supply or commodity shocks and broad-based demand or wage-price dynamics, though in real time the boundary between the two is often contested.
- Expectations anchoring: If households and businesses expect elevated inflation to persist over multi-year horizons, central banks face stronger pressure to maintain a restrictive stance until inflation is clearly converging back toward target.
- Financial conditions and credit stability: Tighter policy and higher market yields transmit through bank lending, corporate debt markets, and asset valuations. Policymakers monitor whether financial conditions are tightening in an orderly way that cools excess demand or creating stress in leveraged segments.
Distinguishing Verified Facts from Analytical Hypotheses
In fast-moving macro weeks, separating confirmed releases from model projections prevents overreaction:
- Known facts consist of officially released data prints (such as inflation readings, consumer survey indices, labor statistics, and reported corporate financial results) and explicit statements or minutes from central bank meetings.
- Educated hypotheses include forecasts of future rate moves, projections of when inflation will return to target, estimates of how much AI capital spending will ultimately yield in productivity, and assumptions about how consumers will allocate holiday or discretionary budgets.
Step-by-Step Analytical Playbook for Macro-Heavy Weeks
Rather than reacting to every headline as it crosses the tape, apply a disciplined five-step sequence whenever inflation, earnings, consumer sentiment, and central bank events converge:
- Anchor on the latest inflation decomposition: Check whether headline and core price measures are moving due to energy/logistics, goods supply constraints, or services/shelter, and note whether near-term or longer-term inflation expectations shifted.
- Cross-check consumer sentiment against real spending mechanics: Compare survey confidence against real income trends, savings behavior, and credit usage to judge whether sentiment reflects near-term price frustration or an imminent pullback in actual outlays.
- Audit corporate earnings for margin quality and capex discipline: Look past headline beats to see how firms handle input costs, whether unit demand holds up, and how capital expenditures are funded.
- Map central bank rhetoric to the rate path: Read speeches, minutes, and policy signals for clues on how policymakers weight upside inflation risks against labor cooling and financial conditions—and compare that tone against market-implied rate expectations.
- Identify cross-asset confirmation or divergence: Verify whether bond yields, credit spreads, and equity sectors agree on the macro story. When yields, credit spreads, and equities diverge, treat headline index moves with caution until the underlying transmission mechanism clarifies.
Limitations and Strategic Action
No analytical framework eliminates macro uncertainty. Economic data is subject to revisions, survey samples can diverge from actual transactions, and geopolitical or financial shocks can alter assumptions abruptly. Treating any single forecast as a certainty is a recurring mistake when inflation and policy paths are contested.
For portfolio managers, corporate operators, and decision-makers navigating this environment, the highest-value strategic move is to stress-test plans against a "higher-for-longer rate and uneven demand" regime rather than betting on a frictionless pivot. For businesses, that means protecting unit economics, locking in supply and financing terms where practical, and tying capital expenditure milestones to demonstrable cash returns rather than optimistic volume assumptions. For investors, it means favoring balance-sheet strength, pricing durability, and cash-flow visibility while sizing positions to absorb rate and valuation volatility without forced selling.